Return on investment
What a new-build investment can mean in practice
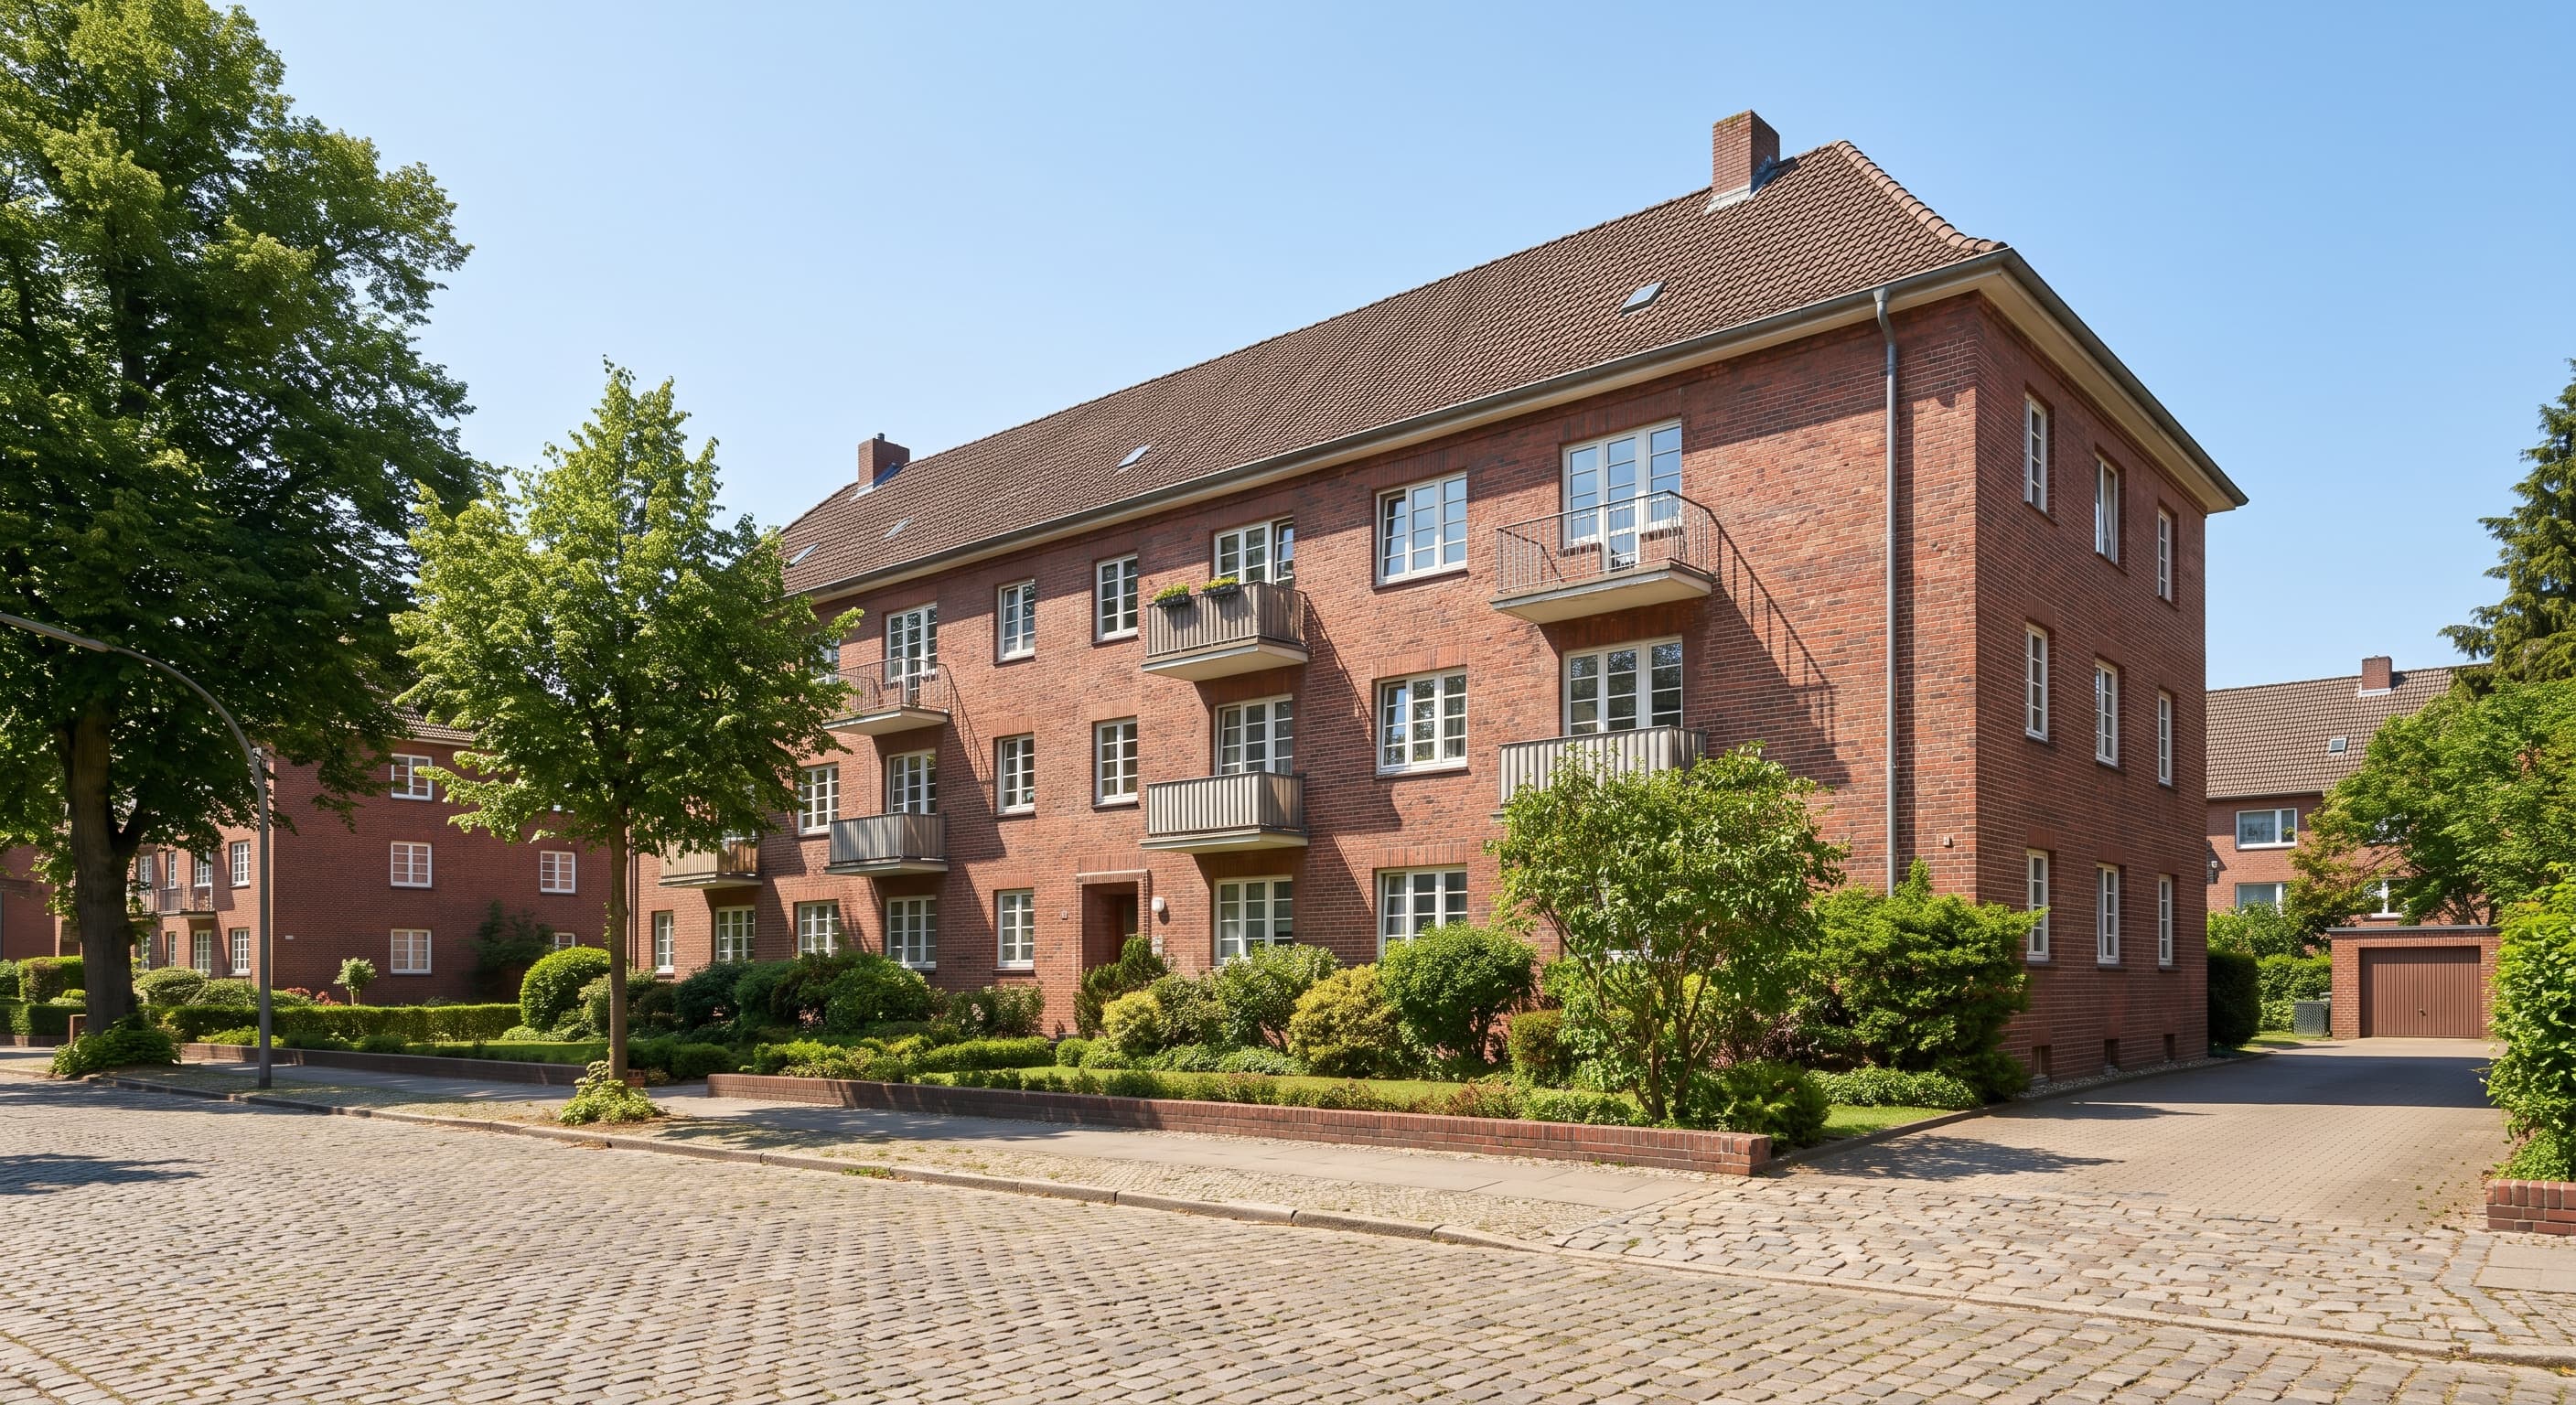
I have calculated what an investment in a new-build property could mean for you in practical terms — from purchase price and rental income to tax savings, monthly cash flow and long-term equity growth.
New-build investment example
I have calculated what an investment in a new-build property could mean for you in practical terms.
Purchase price, including parking space and fitted kitchen
EUR 322,500
- Rental income+ EUR 860*
- Tax savings+ EUR 780*
- Monthly mortgage payment (interest + principal repayment)− EUR 1,394
- Service charges / maintenance provision− EUR 79
EUR 52,500
Tax savings over 10 years*
EUR 148,000
Equity growth over 10 years*
EUR 150,000
Potential KfW subsidised loan*
EUR 49,570
Down payment*
You would largely repay the property through the rental income and tax advantages while building equity and long-term wealth at the same time.
Related pages
German real estate
Why expats invest in German property — and what to check before you buy.
Learn moreTax benefit & depreciation
AfA, special depreciation and concrete examples for new builds and existing stock.
Learn moreHomeloan for expats
Independent mortgage advice for expats who live and work in Germany.
Learn moreAverage figures over a 10-year period. This illustration is non-binding and does not constitute tax, legal or investment advice. It is based on the stated assumptions, including a personal marginal tax rate of 42%; declining-balance depreciation of 5% per annum plus an additional 5% special depreciation allowance pursuant to Section 7b of the German Income Tax Act (EStG); an average nominal interest rate of 3.74% per annum, including a KfW subsidised loan; an average initial repayment rate of 1.5%; continuous full occupancy; and an assumed annual property-value appreciation of 2.5%.
The financing example assumes an equity contribution of EUR 49,570, which essentially covers the ancillary acquisition costs, including construction-period interest and the fitted kitchen. In this example, the financing amounts to 93% of the purchase price.
A low equity ratio increases both interest-rate risk and realisation risk, particularly if the property is sold before the loan has been substantially repaid. The KfW subsidised loan included in this illustration is subject to fulfilment of the applicable eligibility requirements; there is no entitlement to funding.
Do you have any questions?
About the project, the financing options or the potential tax benefits?